Is Mox Credit still worth it? Mox+, cashback and the HK$2,200 welcome: 10 things to know before you apply
Mox Credit switched to a new setup in September: just 1% without Mox+, still 3% at supermarkets, 1.95% on foreign currency, and the welcome of up to HK$2,200 means ticking off four separate tasks. Cashback, fees, the account and the catches, all in one go.
Last updated 2 November 2026
Mox
E6BZQ2Ad / referral links — we may earn a bonus when you sign up.
Full details & steps →Best for
People who hit the supermarket a lot, rarely spend in foreign currencies and like running their account and credit card from one app; or anyone with HK$600,000 in assets who can unlock Mox+ 2%.
Since September, Mox Credit splits people into two camps. If you have HK$600,000 for Mox+, everyday spending earns 2% with no cap, which is strong for a no-annual-fee card; if you don't, you get just 1%, though the uncapped 3% at supermarkets is still there and still useful. Foreign currency spending costs 1.95% in cashback mode, so remember to switch to Asia Miles mode or use another card. The welcome of up to HK$2,200 has to be earned piece by piece: the HK$200 and HK$1,000 are easy to get, but the savings and investment parts mean putting HK$50,000 in.
Pros
- 3% cashback at supermarkets, no cap
- 2% on everyday spending with Mox+, also uncapped
- No annual fee, and no over-limit fee even if you max it out
- One card works as both debit and credit, adjusted instantly in the app
- Switch to Asia Miles mode and foreign currency spending is fee-free in 2026
- High app ratings: 4.8 on the App Store, 4.6 on Google Play
Watch-outs
- Without Mox+, everyday spending earns just 1%
- Foreign currency spending in cashback mode costs 1.95%
- Close your Mox account within 12 months and all your cashback gets clawed back
- Customer service is chat only, and lots of people lately say the wait is long
- The cashback rules have changed many times
- 35.99% effective annual rate, so not paying in full really hurts
Current related offer
Mox offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Mox
Mox’s HK$2,200 headline has several jobs behind it. Type in E6BZQ2 when you open the account during 14 September–20 December 2026 to start the HK$200 credit-card referral; the extra spend, savings and investment rewards have separate deadlines and base conditions, so choose only tasks that fit your finances. Credit involves repayment risk — 借定唔借?還得到先好借!
Requirement: HK$200 referral: Mox Credit approved within 30 days of opening and eligible spend within 30 days of approval. Additional rewards depend on Programme 25 credit/spend, savings and investment conditions.
Medium15-30 minutes to apply, plus card approval and qualifying tasksPayout After you successfully apply for a Mox Credit Card and complete the related welcome tasks under live Mox terms — cash rewards (if any) credit to your Mox account per the referral programme schedule
Verified 2 November 2026 · Ends 20 December 2026
Full claim instructions are on the Mox offer page.
1. What bank is Mox, and is it safe?
Mox Bank is majority-owned by Standard Chartered Bank (Hong Kong), with PCCW, HKT and Ctrip Finance on board as partners. It got its licence in March 2019, launched in September 2020, and is a licensed bank on the HKMA register.
It's a member of the Deposit Protection Scheme, which covers your main account, Goals and time deposits of five years or less, up to HK$800,000 per depositor.
2. One card, two jobs
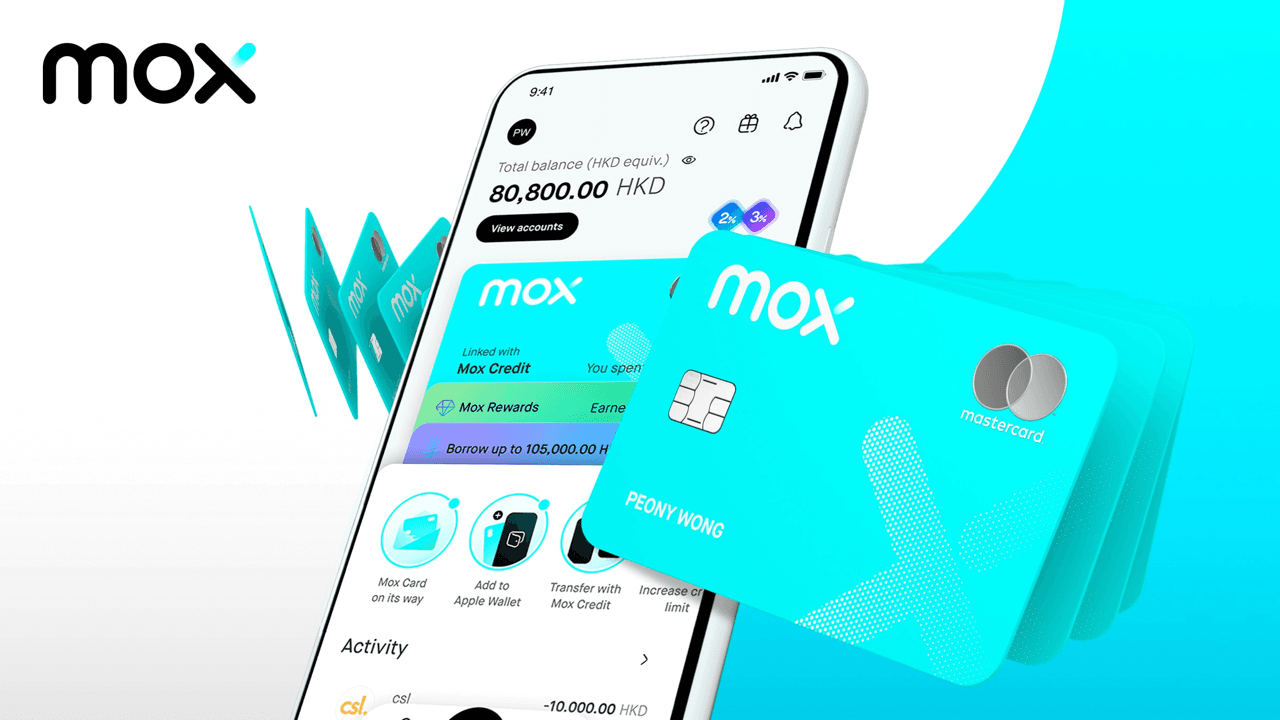
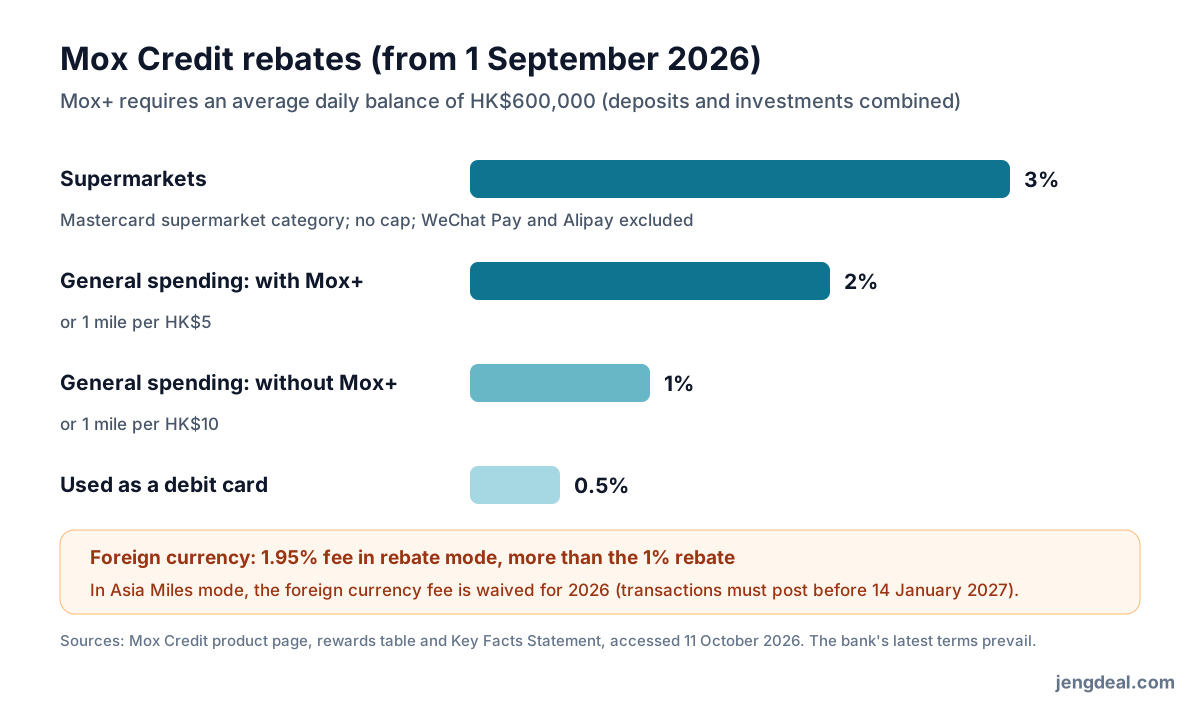
Mox only has one card. Once Mox Credit is approved, the debit card you already have turns into a credit card on the spot, with no new card in the post, and in the app you can choose to pay by debit or credit. Paying by debit still earns 0.5% cashback, with no cap.
The credit card is tied to your Mox account: close the account and the credit limit goes with it. There's no card number printed on the card; the details only show up in the app.
3. The September shake-up: Mox+ or not makes a big difference
From 1 September 2026, your cashback depends on whether you're Mox+. Mox+ needs an average daily balance of HK$600,000 (deposits plus investments), counted month by month; with Mox+, everyday spending earns 2% or 1 Asia Mile per HK$5, and without it just 1% or 1 mile per HK$10. The old trick of getting 2% by having your salary paid in ended on 31 August.
Supermarkets (Mastercard's supermarket category) earn 3% whether you're Mox+ or not, with no cap, but paying through WeChat Pay or Alipay doesn't count. Gambling, cash withdrawals, Octopus top-ups, crypto, transfers, bill payments, insurance premiums and taxes earn nothing at all; refunds take the cashback back off. Switching between cashback and miles mode costs HK$50 each time.
Let's do the maths: spend HK$10,000 a month locally and the gap between 2% and 1% is HK$1,200 a year. Parking HK$600,000 to get that HK$1,200 works out to roughly 0.2% extra a year on that money, and it might do better somewhere else.
4. How does it stack up against other cards?
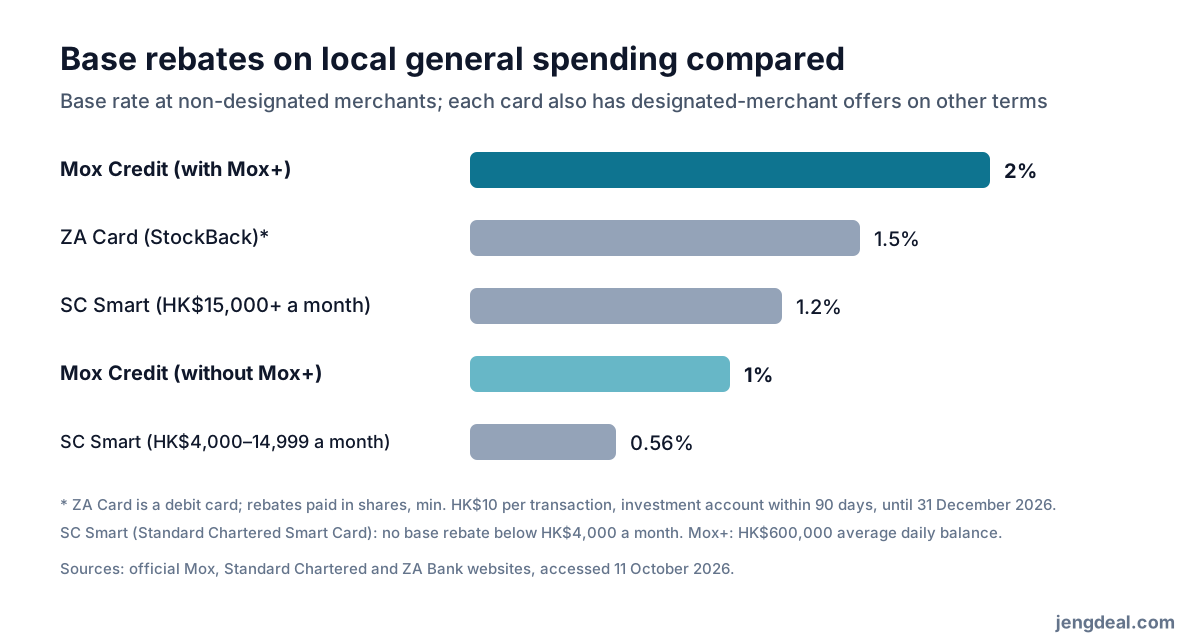
Counting only basic cashback at non-designated merchants: 2% with Mox+ is higher than Standard Chartered Smart Card's 0.56% to 1.2% (depending on how much you spend each month, with no basic cashback under HK$4,000 a month), and higher than ZA Card's 1.5% StockBack, which is paid in shares; 1% without Mox+ lands in the middle.
But every card has its own designated merchants: Standard Chartered Smart Card, for example, gives 5% at designated merchants (counting up to HK$5,000 of designated spending per period), and it charges no foreign currency fee. If you mostly shop at a handful of those places or travel a lot, the answer might be different.
5. Travelling? Remember to switch modes
Mox Credit charges 1.95% on foreign currency spending and overseas merchants, and in cashback mode the 1% or 2% you get back doesn't cover it.
Pick Asia Miles mode and foreign currency spending from 1 January to 31 December 2026 is fee-free, as long as the transactions post by 14 January 2027. If you travel a lot, switch to miles mode first, or use another card that doesn't charge a foreign currency fee.
6. Interest and fees: don't just pay the minimum
Purchase interest is 33.10% a year, with an effective annual rate of 35.99%; cash advances run at an effective 35.93% a year, plus a 3.5% or HK$100 fee (whichever is higher). Pay in full and you get up to 56 days interest-free. The minimum payment is interest and fees, plus 1% of the principal, plus anything overdue, or HK$220, whichever is higher; paying late costs HK$350 or the minimum payment, whichever is lower.
No annual fee, and no over-limit fee even if you max it out. Sending your credit limit out by FPS costs up to 3.5% on anything above the monthly allowance; turning on auto-switch spending costs HK$25 a month. Borrow or not? Only borrow if you can repay!
7. The Mox account itself
The basic savings rate for HKD and USD is just 0.001% a year. From 1 May to 31 December 2026 there's a Mission Bonus Rate: in October you get an extra 1.5% for having your salary paid in, 1% for investing, 0.4% for currency exchange and 0.1% for deposits, up to 3% in total, on up to HK$1,000,000 (HK$5,000,000 for Mox+), recalculated every month.
Time deposits start from HK$1, with the interest paid upfront; take the money out early and the interest already paid comes out of your principal. You can set up to five Goals (HKD only). Withdrawals at local JETCO ATMs are free, Mastercard ATMs cost HK$20 a time and overseas HK$30; currency exchange costs up to 2%; sending USD out through the real-time gross settlement system costs US$20 a transfer; a replacement card is HK$100. No account fee, plus Money Safe and free FPS payments in. Mox+ also gets three free overseas withdrawals a month and a metal card.
8. How to stack up the HK$2,200 welcome
Referral Programme 25 runs from 14 September to 20 December 2026, only for people who have never had a Mox account, with limited spots on a first-come, first-served basis. Type invite code into the Mox app when you sign up (you can't add it afterwards), and finish opening your account on the day you enter the code or within 15 days after.
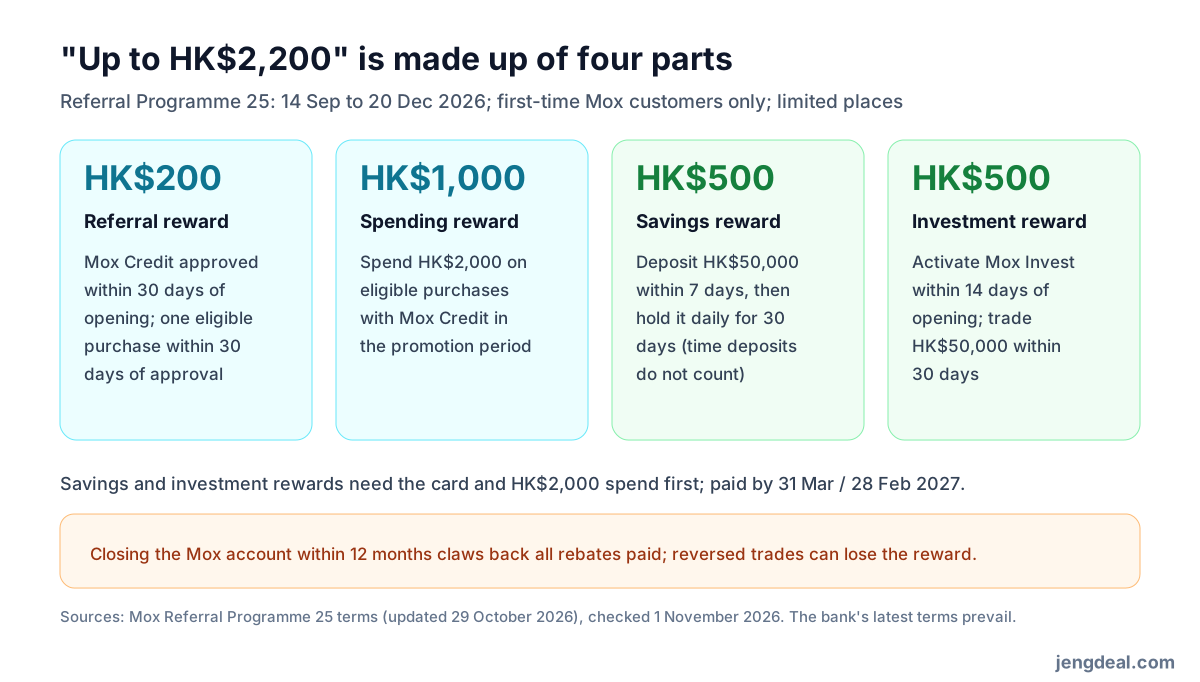
It comes in four parts: get Mox Credit approved within 30 days of opening and make an eligible purchase within 30 days of approval, and you get HK$200; spend HK$2,000 on Mox Credit during the promotion for another HK$1,000; deposit HK$50,000 during the 7-day deposit window and hold it every day for 30 days (time deposits and FlexiBoost don't count) for HK$500; turn on Mox Invest within 14 days of opening and trade HK$50,000 within 30 days for another HK$500. The savings and investment parts only count once you've done the credit card and HK$2,000 spending parts.
The HK$200 lands within 60 days of the eligible purchase posting, and the savings reward is paid on or before 31 March 2027 and the investment reward on or before 28 February 2027; Octopus top-ups through Apple Pay don't count as spending.
9. Who can apply, and how is the credit limit set?
To open a Mox account you need to be 18 or over, with a Hong Kong ID card (permanent or non-permanent both work) and a Hong Kong address. The credit card is approved based on income, job and credit history, and the bank hasn't published a minimum income; you can apply even without a job, but you may need to send in documents.
Your credit limit depends on your monthly income, job and credit history. Asking for a higher limit means sending proof of income; if you're turned down you can't reapply for three months, and students can't ask for an increase. Close your Mox account within 12 months and all the spending cashback already paid gets clawed back.
10. What do users say?
On 11 October 2026, the Mox Bank app scored 4.8 on the App Store (Hong Kong) (92,965 ratings) and 4.6 on Google Play (35,326 ratings). The overall scores are high, but lately the written reviews are more negative than positive.
The most common gripes: cashback rules changing again and again, and welcome spots or conditions people couldn't meet; customer service that's chat only with long waits, and late fees that are hard to get waived; being asked to re-verify at login all the time; credit limits cut or accounts frozen; and cards that won't add to Apple Pay.
Who should go for it, and who should skip it
Go for it: big supermarket spenders; people with HK$600,000 to play the Mox+ 2% game; anyone who likes running their account, savings and credit card from one app.
Skip it: if you often spend in foreign currencies and don't want to switch to miles mode; you're used to paying only the minimum; you need phone customer service; or you might close the account within a year.
FAQ
- What's Mox+?
- An average daily balance of HK$600,000 (deposits plus investments), counted month by month. With Mox+, everyday spending earns 2%; without it, 1%.
- Is it still worth it without Mox+?
- Depends how you spend. Supermarkets still get 3% with no cap and everyday spending just 1%, but there's no annual fee.
- Which mode should I use when travelling?
- Cashback mode charges a 1.95% foreign currency fee; switch to Asia Miles mode and foreign currency spending in 2026 is fee-free, as long as the transactions post by 14 January 2027.
- How do I get the HK$200 referral reward?
- Open an account with E6BZQ2 on or before 20 December 2026, get Mox Credit approved within 30 days of opening, and make an eligible purchase within 30 days of approval. It lands within 60 days of the purchase posting.
- What do I need to do for the HK$2,200?
- Four things: the HK$200 referral, HK$1,000 for spending HK$2,000, HK$500 for depositing HK$50,000 and holding it 30 days, and HK$500 for trading HK$50,000. Spots are limited.
- Is my money protected?
- Mox is a member of the Deposit Protection Scheme, which covers the main account, Goals and time deposits of five years or less, up to HK$800,000 per person.
- What happens if I close the account?
- Your credit limit goes too; close your Mox account within 12 months and all the spending cashback already paid gets clawed back.
Featured in these guides
Double 12 HK Stacking Playbook — Rewards, Forwarding & Cards on Taobao, JD and HKTVmall
Line up your 12.12 strategy across Taobao, JD.com HK and HKTVmall 篤篤賺: spot what stacks with ShopBack and parcel forwarders, avoid instant tracking voids, and run the HK$ maths on card FX fees.
About 9 minGetting a new iPhone in Hong Kong: check the shop, work out the card bonus and avoid trade-in catches, including Duo
Buying in Hong Kong this November 2026? Check Duo, 18 Pro and Air prices and SIM changes, cashback exclusions, four card offers on an HK$10,499 purchase, and why Trade In can shrink your qualifying spend.
9-minute readJengDeal's Hong Kong card welcome offers, November 2026: lower targets, extended deals and annual fees
Four Hong Kong card referral deals checked on 2026-11-17: Mox E6BZQ2, SC Cathay A3872270, Citi HK and the newly extended Amex Explorer window, with actual spending targets, fee waivers, expired WeWa and the debt-consolidation catch.
9-minute readYour Hong Kong credit-card routine: apply, spend, repay and check rewards
Build card rewards around purchases you already need. Follow the welcome tasks, cashback caps, miles checks, overseas payment choices and renewal costs.
8 min readHong Kong bank offers without the trap: funding, lock-ins and cover
Before you open the account, write down when you need the cash. Split the annualised quote into interest over the term, then check new money, fees, early withdrawal and deposit protection.
7 min read