Mintos from Hong Kong: No Bonus, a €50 Review Fee, Tax on Interest and Lenders That Default — 10 Things to Know Before You Invest
Latvian platform Mintos has loans, bonds, ETFs and stocks in one app. Here's what a Hong Konger has to get through to open an account, why the referral bonus isn't for you, what €5,000 actually leaves you after a year and tax, what happens when a lender won't buy back, and how easy it is to get out.
Last updated 24 October 2026
Mintos
N3VOCSAd / referral links — we may earn a bonus when you sign up.
Full details & steps →Best for
Hong Kongers who already have a euro IBAN in their own name, get that lending companies can go bust, don't mind asking the IRD for a residence certificate every year, and only put in money they can afford to lose.
Mintos holds a MiFID II licence from Latvia's central bank, lets you buy ETFs and stocks from €1 and keeps them in custody in your name, so it's a proper regulated platform. But as a Hong Konger you sign up for a few things: approval is case by case, some accounts pay a €50 review fee you never get back, it takes only a passport and SEPA euros from an IBAN in your own name, Smart Cash is off-limits and the referral bonus isn't yours. The real risk is the lending companies: if one won't buy back, the €20,000 investor compensation doesn't cover you either, and in October 2026 cases like Nera Capital are still in recovery. Run the numbers: €5,000 at the 10.33% average rate for a year, with no defaults, leaves about €445 with a tax residence certificate and €365 without. Most Hong Kongers don't need to bother; if you already have a euro account and can stomach the risk, start small.
Pros
- MiFID II licence from Latvia's central bank (Latvijas Banka), licence no. 06.06.08.719/534
- ETFs and stocks sit in segregated custody accounts in your name, apart from Mintos' own money
- If Mintos itself goes wrong, investor compensation covers up to €20,000, wherever you live
- Loans, bonds, ETFs, stocks, real estate and crypto ETPs, all on one platform
- ETFs, stocks and the Secondary Market from €1; Primary Market loans and bonds from €50
- No withdrawal fee, and SEPA Instant usually lands in about 30 minutes
Watch-outs
- Hong Kongers are approved one by one, and some accounts pay €50 up front, refunded never
- Passport only, and only SEPA euros from your own IBAN; your Hong Kong cards won't work
- The referral bonus is for EU/EEA residents only, so Hong Kongers get nothing
- Interest loses 25.5% to tax unless you send a Hong Kong tax residence certificate every year to cut it to 10%
- If a lender won't buy back, your money gets stuck in recovery and you can't sell it
- Smart Cash is closed to Hong Kong tax residents, so idle euros earn zero
Current related offer
Mintos offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Mintos
Mintos, the European platform for loans, bonds, ETFs, stocks, real estate and crypto ETPs, shows up to €125 on its official referral page: €25 plus 1% of your average investments over the first 90 days, with the 1% part capped at €100. The deal: live in the EU/EEA, be 18+, invest at least €1,000 within 30 days of signing up and keep at least €1,000 in until day 90 after sign-up. Only loans, bonds, ETFs, crypto and real estate count; stocks and Smart Cash aren't on the list. Straight talk: Hong Kong residents can't get the bonus, and UK residents can't even register. Capital at risk; you can lose money. Not investment advice.
Hong Kong residents can't get this bonus. Mintos' referral terms limit the programme to residents of the EU/EEA, and Mintos only considers accounts for people from other countries case by case. Mintos is licensed and supervised in Latvia (Latvijas Banka). Capital at risk. This is not investment advice.
Requirement: €1,000+ invested within 30 days of sign-up, kept in until day 90 after sign-up (EU/EEA residents only)
Hard15-30 minutes to register and verify, then a 90-day holding periodPayout The bonus is credited within 7 days after the 90-day holding period ends (counted from your registration date); Mintos processes the 1% part within 7 working days, per the Mintos Help Center
Verified 24 October 2026
Full claim instructions are on the Mintos offer page.
Thing 1: Can Hong Kongers even use it?
Yes, but it isn't automatic. Mintos takes EU/EEA and Swiss citizens and residents aged 18 and over; Hong Kongers are looked at case by case and may be asked for proof of address. US citizens and residents and UK residents can't open an account at all, so if you're heading to Britain, remember you can't keep investing here once you move. One account per person.
The referral bonus is a definite no: clause 14.3 of the referral terms, version 1.20 (21 September 2026), says the invited person has to live in the EU/EEA. Whether you open an account or not, don't make the call because of a bonus.
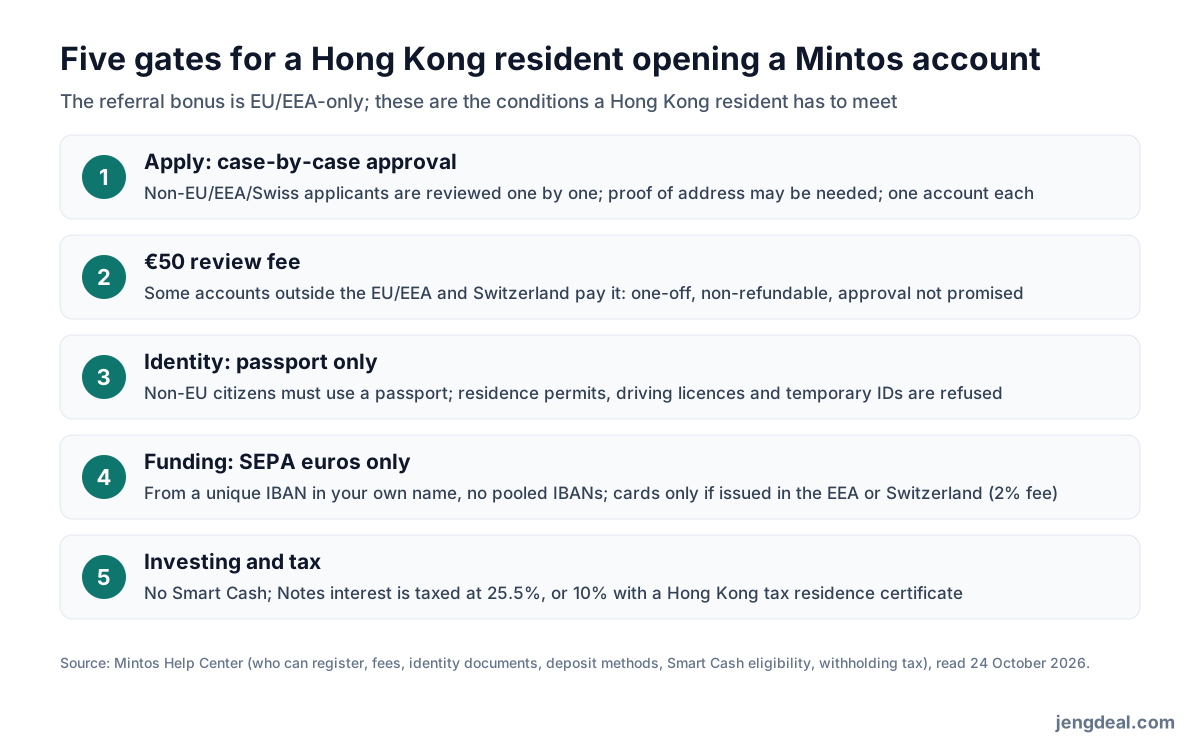
Thing 2: The hoops for opening and funding
Hoop one is money: some individual accounts living (or tax resident) outside the EU/EEA and Switzerland pay a one-off €50 review fee first, non-refundable and with no promise of approval. Hoop two is ID: non-EU citizens can only use a passport, and residence permits, driving licences and temporary IDs are all refused.
Hoop three is getting money in: SEPA euro transfers only, either straight from a bank in the SEPA zone or through a payment service that gives you a unique IBAN in your own name (Mintos names Wise and Revolut); shared or pooled IBANs are refused. Card top-ups only work with cards issued in the EEA or Switzerland and cost 2%, so your Hong Kong card is out.
Thing 3: Is it licensed, and what if it goes wrong?
It's run by AS Mintos Marketplace (company no. 40103903643, Skanstes iela 50, Riga), which got its investment firm licence (06.06.08.719/534) from Latvia's central bank, Latvijas Banka, on 17 August 2021 and is regulated under the EU's MiFID II: it can execute orders, manage portfolios, give investment advice and hold financial instruments for clients. The group also has an e-money licence, and KPMG Baltics audits its annual reports. The licence works in 29 EU and EEA countries, but Mintos isn't licensed in Hong Kong, so treat it as an overseas platform. You'll also fill in a MiFID suitability test, and depending on your answers some portfolios, like Core Loans, may be blocked.
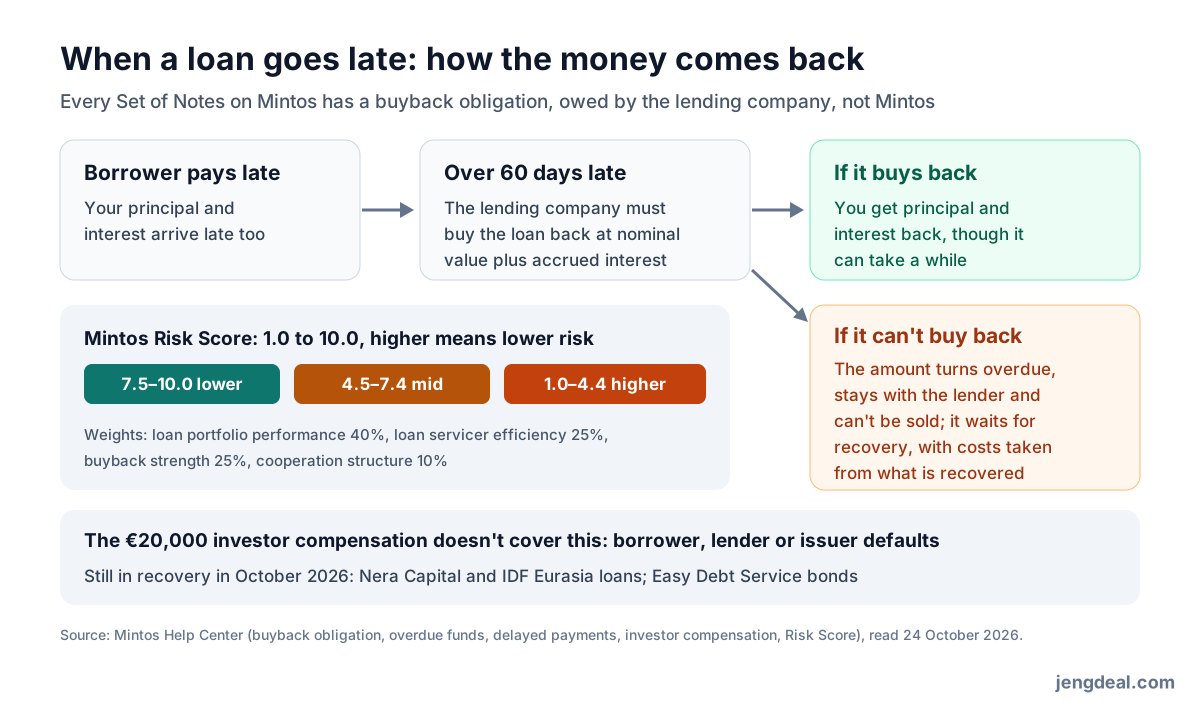
Mintos is in Latvia's investor compensation scheme: if Mintos itself can't give back your financial instruments or cash, you're covered up to €20,000, wherever you live. Falling prices, borrowers or lenders or issuers going bust, and having no market to sell into are not covered. Idle cash sits in safeguarding accounts at EU and Swiss banks or in qualifying money market funds, and it isn't a deposit; ETFs and stocks are held in your name. Hong Kong's Investor Compensation Fund only covers Hong Kong licensed intermediaries on products traded on the Hong Kong exchanges (up to HK$500,000), so it doesn't reach Mintos.
Thing 4: What can you actually buy?
The headline product is loan Notes: a special purpose company in the Mintos group bundles 6 to 20 similar loans into a Set with its own ISIN, from €50 per Set on the Primary Market and €1 on the Secondary Market. Don't want to pick? Core Loans (0.39% a year) or Custom Loans (0.29%) invest for you. On 24 October 2026 the statistics page showed a current average interest rate of 10.33% on the platform's loans; that's an interest rate, not what's left after defaults.
There are also bonds (from €50, including the High-Yield Bonds portfolio), real estate Notes (€50), ETFs (€1 each, €50 for the Core ETFs portfolio), and stocks and crypto ETPs (both from €1). Mintos charges nothing on ETFs, whose own costs are usually under 0.25% a year; stocks are commission-free, with a currency conversion for non-euro shares. Smart Cash parks money in a BlackRock euro liquidity fund, but Hong Kong tax residents can't use it, so idle euros just sit there earning nothing.
Thing 5: What if borrowers stop paying?
Every Set of Notes listed now comes with a buyback obligation: once a loan is more than 60 days late, the lending company has to buy it back at nominal value plus accrued interest. So when a borrower defaults you'll usually still get paid, just later; the big risk is the lending company itself running out of money to buy back, and then you may not get paid at all. Anything not bought back turns "overdue", stays with the lender, can't be sold and just waits for recovery; recovery costs come out of what's recovered, but never more than that.
In October 2026 Mintos is still posting delayed-payment updates for Nera Capital and IDF Eurasia (Fintech Finance, Biznes Zaim) loans and Easy Debt Service bonds. airBaltic filed for Chapter 11 reorganisation in the US on 14 September 2026, aiming to finish around June 2027, and nobody has said yet how its bond will be treated. Meanwhile Eleving Group may buy back loans early after a new bond issue: you get principal plus interest, then the interest stops and you have to find somewhere else to put the money.
To size up a lender, check the Mintos Risk Score: 1.0 to 10.0, higher means lower risk, with 7.5 and up lower risk and 4.4 and below higher risk. It's built from loan portfolio performance 40%, loan servicer efficiency 25%, buyback strength 25% and cooperation structure 10%. Use it as a guide; spreading your money is what actually protects you.
Thing 6: Tax comes off the interest first
Interest on Notes and Fractional Bonds is taxed in Latvia before you see it, at a standard 25.5% for tax residents outside the EU/EEA. Hong Kong and Latvia signed a comprehensive double tax agreement on 13 April 2016, in force in Hong Kong from the 2018/19 year of assessment; hand over a qualifying tax residence certificate and the rate drops to 10%. The certificate needs your full name and tax ID, has to confirm you're tax resident this year, must say it applies to income from Latvia, and has to be in English or Latvian.
You get it from Hong Kong's Inland Revenue Department: fill in IR1314B through the eTAX Individual Tax Portal or by post, and the IRD aims to reply within 21 working days of a complete application. It usually issues one certificate per agreement per year, so you'll be doing this annually. Tax over-withheld in the past three years can be reclaimed from Latvia's State Revenue Service (VID), one application per Note issuer, signed off by your local tax office, so it's a fair bit of admin. Mintos sends a tax statement every year.
Thing 7: Do the maths on €5,000 for a year
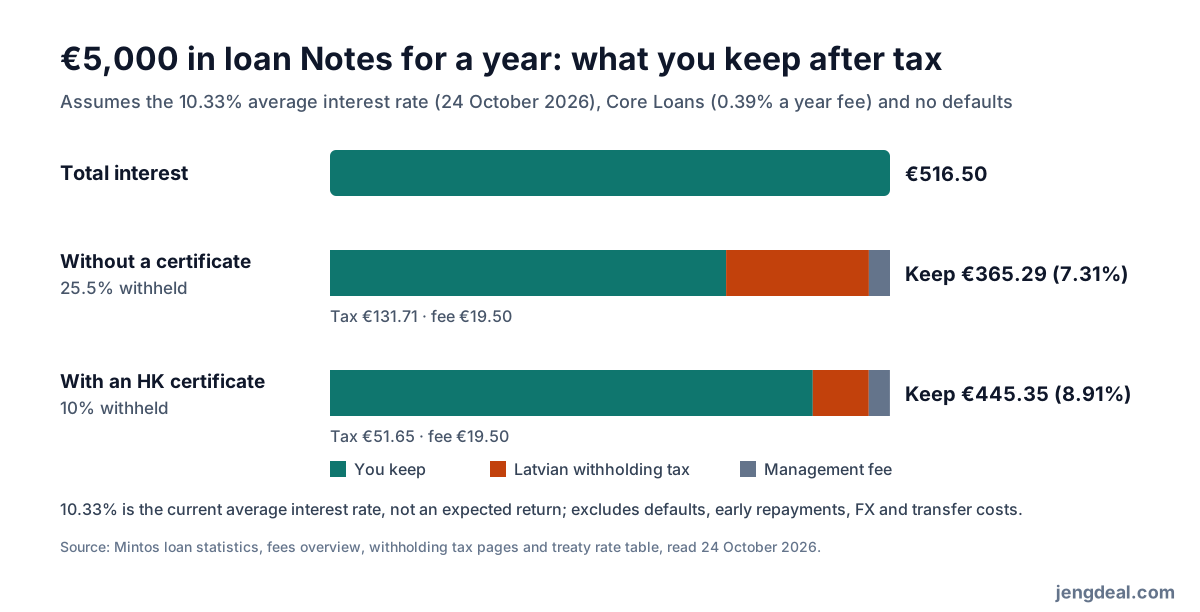
Say €5,000 goes into loan Notes through Core Loans for a year at the 10.33% average rate, with no defaults: €516.50 of interest and a €19.50 management fee. Without the certificate, 25.5% tax takes €131.71 and you keep €365.29, about 7.31%; with it, 10% takes €51.65 and you keep €445.35, about 8.91%. That's roughly €80 a year, so getting the certificate is a no-brainer.
That sum leaves out defaults, cash sitting idle after early repayments, exchange rates and transfer fees. Everything's in euros, so its value in Hong Kong dollars moves with the euro rate; and if one lending company stops paying, part of your money can be stuck for years and the real return can be a lot lower.
Thing 8: Fees, and what it costs to get out
Management fees: Core Loans and legacy loan portfolios 0.39% a year, Custom Loans 0.29%, the High-Yield Bonds portfolio 0.39% from 1 January 2026 and Smart Cash 0.19%, all taken automatically from the portfolio. Crypto ETPs cost 0.49% a trade (at least €0.99); currency exchange starts at 0.50%; card, Apple Pay or Google Pay top-ups cost 2%. If there's been no investing, selling, depositing or withdrawing for 360 days and you only hold loans, there's a €4.90 inactivity fee on the 1st of each month. Bank transfer deposits, withdrawals, manual bond buys and trading ETFs and stocks cost nothing from Mintos.
Want out early? Notes, bonds and real estate Notes normally run to maturity, so cashing out early means selling on the Secondary Market for 0.85% of the sale price, and Mintos says plainly it can't promise a buyer, or even that the Secondary Market will always exist. Core Loans only cashes out investments that still meet the portfolio's rules (for example, a Set with no more than 20% late exposure and a Risk Score of at least 3.5), and overdue money can't be sold at all.
Idle euros can come out any time: about 30 minutes to an account with SEPA Instant, one to two business days otherwise. To close your account, ask in the Mintos Assistant chat and Mintos replies within 5 business days; the balance has to hit zero first. Meanwhile you can't invest or deposit, but you can still withdraw, sell and download statements, and any money still in recovery keeps the account open.
Thing 9: The referral bonus and our code
For friends who live in the EU/EEA: sign up through a referral link, verify your ID, invest at least €1,000 within 30 days and keep at least €1,000 in until day 90, and you get a fixed €25 plus 1% of your average investment over the first 90 days, with the 1% part capped at €100. Loans, bonds, ETFs, real estate and crypto ETPs count; Smart Cash doesn't. Clause 11 of the terms counts the 1% only on the amount above €1,000, while the Help Center uses the whole average: on a €5,000 average that's €65 in total versus €75. It lands within 7 days after the 90 days end, with the 1% part processed within 7 working days.
To be upfront: N3VOCS is our referral code. The programme is EU/EEA-only, so a Hong Konger who signs up through our link gets no bonus; no misunderstandings there. If you do go ahead, sign up through the link on this page (code ).
Thing 10: What do users say?
Checked on 24 October 2026: the Mintos app scores 3.8 on the German App Store (438 ratings), 3.3 in Spain (152), 4.0 in France (63) and 4.7 in Latvia (68); it's downloadable on the Hong Kong App Store but has no ratings there, and it isn't on the UK App Store. Google Play has it at 3.5 to 3.8 depending on region, from about 1,860 reviews, with over 100,000 downloads.
The biggest gripes: money stuck in recovery for years, with buybacks offering no protection when a lender collapses; Nera Capital stopping payments in 2026; the app crashing on launch on some iPhones after a mid-September update; support that goes through an AI bot before you reach a human; monthly fees on idle loan-only accounts; promo bonuses not paid as expected; and too many menus. The fans mostly praise the product range and long-term returns.
Who should play, who should pass
Play if you've got a euro IBAN in your own name, can live with money being stuck for a long time, don't mind getting a tax residence certificate every year, and are only using a small slice of money you can afford to lose to diversify; or if you mainly want cheap entry into European-listed ETFs and are fine with an overseas platform's protections.
Pass if you're a Hong Konger chasing the referral bonus, need your money on call, only have Hong Kong bank accounts and cards with no euro IBAN, are planning to move to the UK, or think of it as a deposit you can't lose money on.
FAQ
- Can Hong Kongers open a Mintos account?
- Yes, but it's case by case, and some accounts pay a non-refundable €50 review fee first. Passport only, and funding is SEPA euros from a unique IBAN in your own name only.
- Do I get a bonus with the referral code?
- Not as a Hong Konger. Clause 14.3 of the terms requires the invited person to live in the EU/EEA, so even hitting the investment target gets you nothing.
- Is Mintos a legit platform?
- Yes, it's a MiFID II investment firm licensed and supervised by Latvia's central bank (06.06.08.719/534), though it isn't licensed in Hong Kong.
- What happens to my money if Mintos goes bust?
- If Mintos itself can't return your assets or cash, investor compensation covers up to €20,000, and your ETFs and stocks are held in your name. Borrower or lender defaults aren't covered.
- How much tax do I pay on interest?
- Notes and Fractional Bonds interest loses 25.5% up front; send a Hong Kong IRD residence certificate that says it applies to income from Latvia and it drops to 10%, renewed every year.
- How fast can I get my money back?
- Idle euros come out free any time, in about 30 minutes via SEPA Instant. Money in loans and bonds waits for maturity, or you sell on the Secondary Market for 0.85% and hope someone buys.
- How do I get money in?
- Mintos only takes SEPA euros from a unique IBAN in your own name, like a bank account in the SEPA zone or a payment service with a personal IBAN. Hong Kong dollar bank accounts and Hong Kong cards can't fund it directly.