Is the Citi credit card referral worth it? HK$1,200 on the Cash Back Card for HK$5,000 spend: 10 things to know first
Apply for a Citi card through a referral and new customers get from HK$1,200 for HK$5,000 of spend in the first 2 months. The catch: a HK$1,800 annual fee from year two, a clawback if you cancel within a year and a 1.95% foreign-currency fee. Which of the eight cards to pick, what spend counts and when the money lands, all in one go.
Last updated 14 November 2026
Citibank Hong Kong (花旗銀行)
Ad / referral links — we may earn a bonus when you sign up.
Full details & steps →Best for
Hong Kongers who haven't held or cancelled any Citi principal credit card in the past 12 months, have roughly HK$5,000 of spending coming up in the first 2 months (spread over both months) and clear the card in full every month. If you eat out a lot, the Cash Back Card fits nicely.
Apply for the Citi Cash Back Card through our referral link, spend HK$5,000 in the first 2 months after the card is issued with at least one transaction each month, and new customers get a HK$1,200 cash rebate. Add the 1% to 2% everyday rebate and year one pays back roughly a quarter of what you spend, with the first-year annual fee waived. That's the real draw. The Rewards Card also pays HK$1,200; the Octopus Platinum Card pays HK$1,800 but needs one extra HK$500 automatic add-value; PremierMiles pays 240,000 points, about 20,000 miles at today's rate. Watch out for the HK$1,800 annual fee from year two (Citi only promises a first-year waiver), the welcome clawback if you cancel within a year, and the 1.95% foreign-currency fee that eats almost all of the Cash Back Card's 2% overseas rebate. The app has also been crashing a lot lately, so leave yourself time to activate the card.
Pros
- Spend HK$5,000 in the first 2 months (at least one transaction a month) for HK$1,200, which with everyday rebates pays back about a quarter in year one
- Cash Back Card: 2% on local dining, local hotels and foreign-currency spend, 1% on everything else, no cap and nothing to register
- Cash Back, Rewards Mastercard, PremierMiles and Octopus Platinum all waive the first-year annual fee
- Pick any one of eight cards: miles fans can take 240,000 PremierMiles points, heavy commuters the Octopus Platinum's HK$1,800
- Welcome and everyday rebates go straight onto your card account to offset your balance, nothing to redeem
- The whole application is online and Citi puts it at about 5 minutes on average
Watch-outs
- HK$1,800 principal-card annual fee from year two; Citi only promises the first-year waiver and won't refund a fee once paid
- Cancel the card within a year of issue and Citi can take the welcome rebate back off your account
- 1.95% foreign-currency fee leaves the Cash Back Card's 2% overseas rebate at about 0.05%, and in-store spend at UK and EEA merchants only earns 1%
- Octopus top-ups, e-wallet top-ups, FPS, bill payments, tax and insurance premiums don't count towards the HK$5,000
- Held or cancelled any Citi principal credit card in the past 12 months? You're out, and so are full-time students at local tertiary institutions
- Recent Citibank HK app reviews are mostly one-star, with frequent crashes and failed ID checks
Current related offer
Citibank Hong Kong (花旗銀行) offer pageAd / referral links — we may earn a bonus when you sign up.
Provider
Citibank Hong Kong (花旗銀行)
New to Citi? Apply through our referral link by 4 January 2027, spend HK$5,000 on a Citi Cash Back or Citi Rewards Card in the first two months (at least one swipe each month) and HK$1,200 lands in your card account. Fancy the Citi Octopus Platinum Card instead? Add one HK$500 auto-reload and it's HK$1,800. 借定唔借?還得到先好借!
Requirement: HK$5,000 eligible spend in the first 2 months after the card is issued, with at least 1 eligible swipe each month (Octopus Platinum: plus one HK$500 auto-reload); Octopus and e-wallet top-ups, FPS, bills, tax and insurance don't count
Medium5–10 minutes to apply online, then approval, activation and two months of spendingPayout Cash rebate within 5 calendar months after the month you hit the spend, straight into the new card account
Verified 14 November 2026 · Ends 4 January 2027
Full claim instructions are on the Citibank Hong Kong (花旗銀行) offer page.
Thing 1: What is this referral programme?
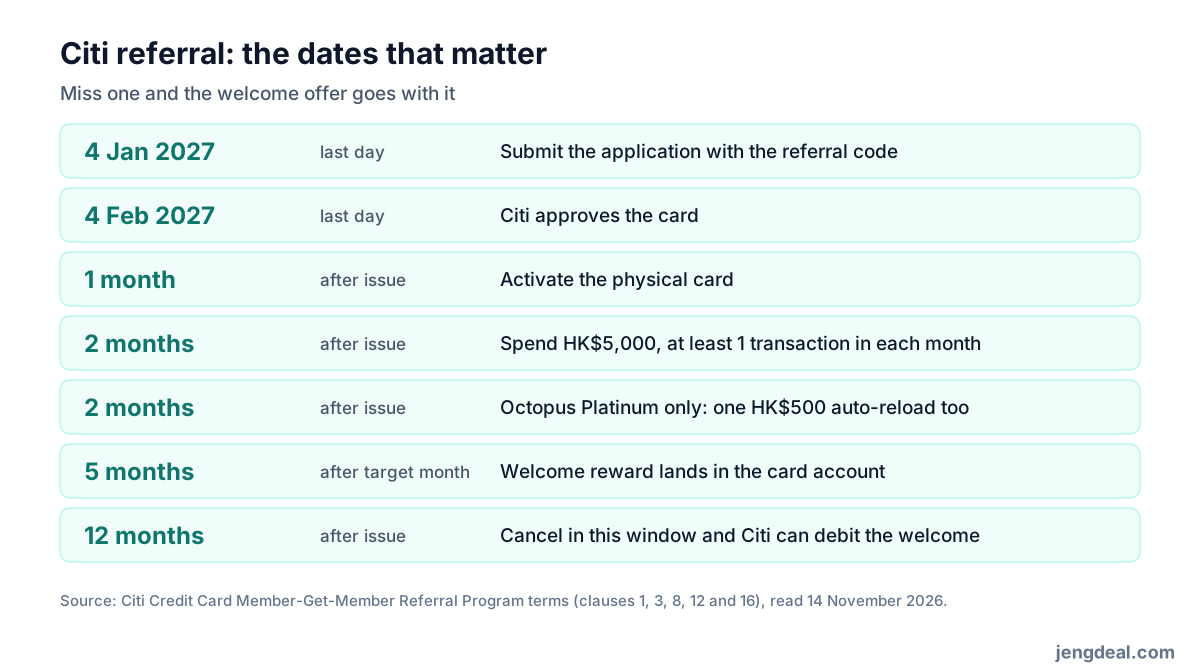
Citi credit cards are issued by Citibank (Hong Kong) Limited, a licensed bank on the HKMA's register. The "Citi Credit Card Member-Get-Member" referral programme runs until 4 January 2027 (it started on 1 July 2026, both days included). To get the referral welcome offer, you have to submit your application for a designated Citi principal card with the unique referral code inside that window.
A credit card is borrowing, not a deposit, so there's no deposit protection, and if you don't clear the bill by the due date you pay interest. Every number below comes from Citi's referral terms, Key Facts Statement and card product pages; if Citi updates them, its latest version wins.
Thing 2: Eight cards, eight welcome offers, up to HK$1,800 cash
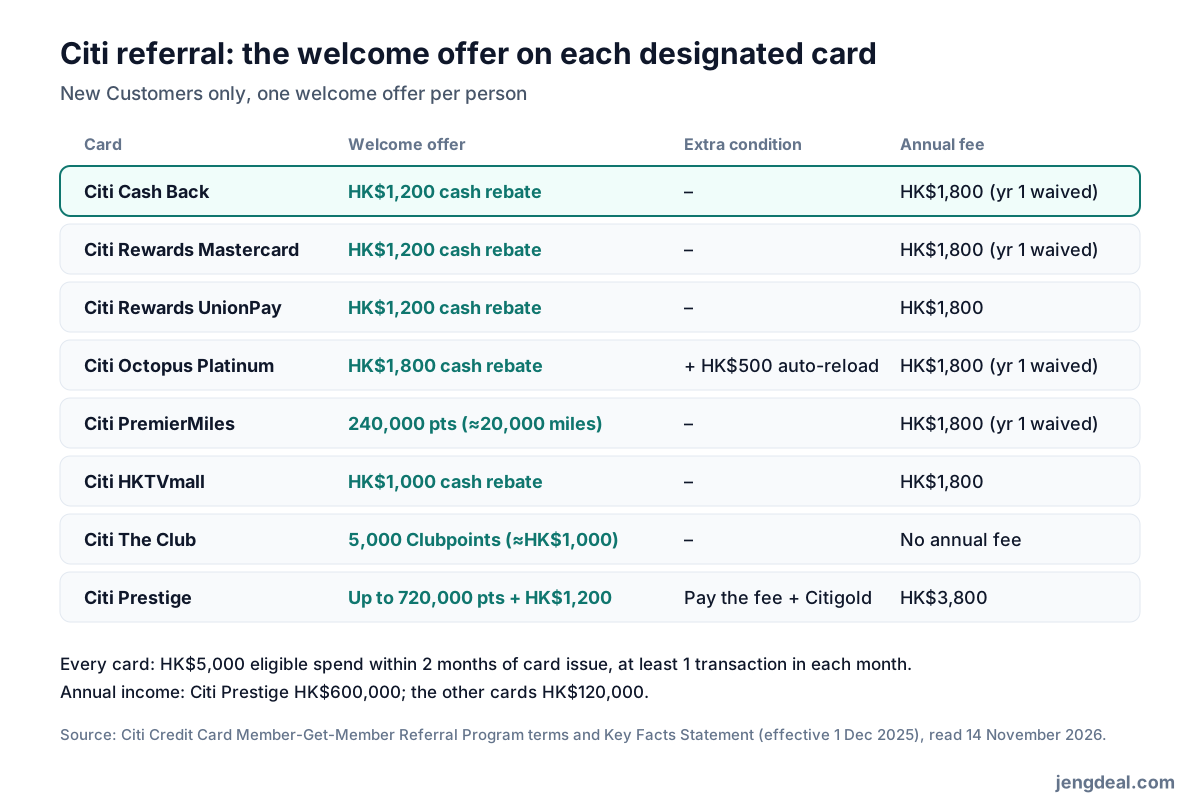
You need to be a new customer and get approved for the principal card of one of these cards through the referral link. It's one welcome offer per person, and once you pick it on the application form you can't switch. Citi Cash Back, Citi Rewards Mastercard and Citi Rewards UnionPay: HK$1,200 cash rebate; Citi Octopus Platinum: HK$1,800 cash rebate; Citi PremierMiles: 240,000 points, which is 20,000 miles at the current conversion rate; Citi HKTVmall: HK$1,000 cash rebate; Citi The Club: 5,000 Clubpoints, worth HK$1,000 at 5 points to HK$1.
The condition is the same for all of them: HK$5,000 or more of eligible spend within the first 2 months after the card is issued, with at least one eligible transaction in each month. The Octopus Platinum Card also needs at least one HK$500 Octopus automatic add-value transaction.
Citi Prestige plays a different game: pay the HK$3,800 first-year fee for 360,000 points; hold or open a Citigold or Citigold Private Client account during the reward period for another 360,000 points; and hit the same HK$5,000 spend for a HK$1,200 cash rebate on top. But Prestige needs an annual income of HK$600,000 or more, so most people can skip it.
Thing 3: Why we lead with the Cash Back Card
Because it's the easiest to work out: local dining (paid in HKD at merchants classed as restaurants), local hotels (paid in HKD) and foreign-currency retail spend earn a 2% cash rebate, everything else 1%, all with no cap, no registration and no categories to choose. The 2% already includes the 1% basic rebate.
Read the small print: restaurants inside hotels, banquets, private parties, and food outlets inside department stores and clubhouses don't count as dining. In-store foreign-currency spend at merchants in the UK and EEA countries doesn't get the 2%, but online spend does. Everyday rebates only land on your next statement once they reach HK$200; you can use them to offset your balance but not to pay the minimum payment, and anything not yet credited is lost if the account closes.
The downsides are obvious too: no miles, no points transfers, just 1% on ordinary local spend, and the 2% overseas rebate is almost wiped out by the 1.95% foreign-currency fee (we do the maths in Thing 8). It suits people who want plain cash back and mostly spend on local dining and hotels.
Thing 4: When do Rewards, Octopus or PremierMiles beat Cash Back?
The Citi Rewards Card also pays a HK$1,200 welcome. Day to day, shopping and entertainment categories such as department stores, fashion, cosmetics, cinemas, concerts, theme parks and streaming platforms earn 8.1 points per HK$1 (3% if you redeem for cash rebate); local mobile payments like Apple Pay, Google Pay and Samsung Pay earn 2.7 points (about 1%); everything else earns just the 1 basic point. Bonus points cap out at 113,400 per statement cycle, which is about HK$15,970 of shopping and entertainment spend on its own.
The Citi Octopus Platinum Card has the biggest welcome, HK$1,800, but you also need at least one HK$500 automatic add-value, and that top-up itself doesn't count towards the HK$5,000. The card's Octopus transport rebate needs registering first: spend HK$4,000 in eligible transactions in a month and MTR, bus, green and red minibus, ferry, tram and taxi fares earn 15% back in Octopus Cash (up to HK$300 a month), so HK$800 of fares a month gets you HK$120; spend HK$10,000 in a month and tunnel tolls, parking, EV charging and designated cross-border transport earn 5% more (up to HK$500 combined); it runs until 30 June 2027. Octopus Cash can only offset later automatic add-value transactions. Also, if your income falls short, Citi may issue the Octopus Gold Card instead, and the Gold card isn't a designated card for the referral.
Citi PremierMiles pays 240,000 points, which is 20,000 miles at the current 12 points per mile. Day to day, local spend earns 1 mile per HK$8 and foreign currency 1 mile per HK$4, improving to HK$3 per mile when eligible spend reaches HK$20,000 in the statement cycle. Each transfer to an airline programme costs HK$200, with a minimum of 18,000 points. Compared with HK$1,200 in cash, 20,000 miles only win if each mile is worth more than HK$0.06 to you, which comes down to how you redeem.
The Citi HKTVmall Card (HK$1,000) and The Club Card (5,000 Clubpoints, no annual fee) have smaller welcomes and only make sense if you already use those platforms a lot; Prestige is covered above.
Thing 5: Do the maths: what does a foodie get for HK$5,000?
Say you take the Cash Back Card and spend HK$2,500 a month at local restaurants for the first 2 months after it's issued, HK$5,000 in total: that's the HK$1,200 welcome plus a 2% dining rebate of HK$100, so HK$1,300, or 26% of what you spent. If it's ordinary local spend at 1% instead, it's HK$1,250 (25%). The first year's fee is waived, so as long as you clear the bill every month, that HK$1,300 is all yours.
Year two is where you need to be sharp. Keep eating out at HK$2,500 a month and a year's HK$30,000 at 2% earns HK$600, but the principal-card fee is HK$1,800, so you're HK$1,200 down. To earn the fee back through rebates you'd need HK$180,000 a year at 1%, or HK$90,000 even at 2%. Citi hasn't published how to get the year-two fee waived, so if you want to keep the card, ask Citi before the fee is charged.
Spending in foreign currency on holiday: 2% rebate minus the 1.95% fee leaves about HK$0.50 extra per HK$1,000; in-store at UK or EEA merchants you only get 1%, so you're down 0.95%. Pay in HKD outside Hong Kong or to merchants not registered in Hong Kong and there's a 1% fee, which just cancels out the 1% basic rebate. So the Cash Back Card isn't your main travel card.
Thing 6: Do you count as a "new customer"?
The welcome offer is only for "new customers": you don't hold any Citi principal credit card now, and you haven't held or cancelled one in the past 12 months, counting from the month you apply. If you're not a new customer, it isn't a successful referral and there's no welcome offer.
Other limits: full-time students on degree or post-secondary diploma programmes at Hong Kong tertiary institutions can't take part; US persons can't either; nor can residents of the EU, the EEA, the UK, Switzerland, Brazil, New Zealand, Turkey, the UAE and the other places listed in the terms. You can only be referred once during the promotion; if you apply again with a different referral code, the first successful referral counts. Anyone already successfully referred in another Citi referral programme is out, self-referral doesn't work, and Citibank staff can't join.
The general rules: aged 18 or over with an annual income of HK$120,000 or more (HK$600,000 for Prestige). The product pages ask for a colour copy of your Hong Kong Permanent Identity Card (signed), recent proof of address, and your latest 1 month's payslip, 3 months of payroll account statements or other proof of assets; the Octopus Platinum and Rewards UnionPay pages also say you must hold a Hong Kong Identity Card. If you're not a permanent resident, check with Citi before you apply.
Thing 7: What spend counts, when the money lands, when Citi can take it back
The HK$5,000 builds up over the first 2 months from the card issue date. Posted spend on the principal and supplementary cards counts, and so do billed monthly instalments of merchant instalment plans. You need at least one eligible transaction in each of the two months; doing it all in one month isn't enough. None of this counts: FPS, Octopus top-ups (including via e-wallets), cash advances, balance transfers, cash-out and instalment programmes, tax payments, online or utility bill payments, insurance, charity donations, Citi PayAll, fund contributions, fees and charges, casino transactions, and anything unposted, cancelled or refunded.
The card must be approved by 4 February 2027, and you have to activate the physical card within 1 month of issue. Cash rebates land on the new card account within 5 calendar months after the month you hit the target; PremierMiles points also arrive within 5 calendar months; Prestige's fee points arrive 2 calendar months after the first-year fee is fully paid. For example, card issued in December 2026, target hit in January 2027: the rebate lands by the end of June 2027 at the latest.
The card has to stay valid and in good standing through the whole promotion and reward period. Cancel it within a year of issue and Citi can take the face value of the welcome offer back off your card account; if spend that counted towards the target is later cancelled or refunded, Citi can claw back the matching reward too. The welcome offer can't be transferred or swapped for cash.
Thing 8: Annual fee, interest and foreign-currency fees
From the Key Facts Statement effective 1 December 2025: the principal-card annual fee on Cash Back, Rewards, PremierMiles, Octopus Platinum and HKTVmall is HK$1,800, supplementary cards HK$900; Prestige is HK$3,800; The Club Card has no annual fee. Cash Back, Rewards Mastercard, PremierMiles and Octopus Platinum state a first-year fee waiver. The card agreement says annual fees aren't refunded.
Purchase interest is 31% a year, an APR of 34.28%; cash advances carry an APR of 35.81% plus HK$100 each time. Pay in full and you get up to 58 interest-free days. The minimum payment is interest and charges plus 1.5% of the statement balance (at least HK$300 a month); a late payment costs HK$300 or the previous minimum payment, whichever is lower; going over your limit costs HK$180 per statement; paper statements are HK$10 a month; Citi PayAll charges up to 4% of the payment.
The foreign-currency fee is 1.95%. Spend in HKD outside Hong Kong or with merchants not registered in Hong Kong (overseas online shops, say) and Visa and Mastercard cards are charged 1%; UnionPay cards aren't. If an overseas merchant offers to bill you in HKD, its rate and fees can cost more than the foreign-currency fee, so paying in the local currency is the safer bet.
Thing 9: What do Citibank HK app users say?
Activating the new card, checking rebates and managing the account mostly happen in the Citibank HK app. On 14 November 2026 it rated 4.60 on the Hong Kong App Store (61,150 ratings, version 8.9.5, updated 26 October 2026) and 2.5 on Google Play (about 10,700 reviews, more than 500,000 downloads, updated 15 October 2026).
The overall score looks fine, but recent reviews are mostly negative: of the 150 most recent App Store reviews (10 July to 12 November 2026), 114 were one-star and just 7 five-star. The top complaints: crashing the moment it opens after updating to iOS 27.3; ID card and selfie checks failing again and again after switching phones; card activation and other features not working; and a hard-to-use interface. You must activate the physical card within 1 month of issue, so leave yourself time, and switch to the card activation page on Citi's website if the app won't play along.
Thing 10: How to apply, activate and cancel
Open Citi's referral application page through our link and the unique code box should already be filled in. Pick your relationship to the referrer, choose your card and tap the apply button, and Citi opens an online application form with the referral code attached. The terms say you must submit the application with the referral code, so check the code has carried over before you hit submit. The unique code our link fills in is our referral code.
Once approved, activate the physical card in the app or on Citi's website within 1 month of the issue date, then hit the spend target above within the first 2 months. If you went for the Octopus Platinum Card, make sure at least one HK$500 automatic add-value goes through in that same window.
Want to cancel? Just tell Citi you're ending the card agreement, for example by calling Citibank's phone banking on 2860 0333 (Prestige: 2860 0338). On termination Citi can ask you to repay the whole balance straight away, and cancelling the principal card cancels the supplementary cards too. Remember: cancel within a year and the welcome offer can be taken back, annual fees already paid aren't refunded, and Cash Back rebates under HK$200 that haven't been credited are lost when the account closes.
Who should go for it, who should skip it
Go for it: you've had no Citi principal credit card in the past 12 months, you've got HK$5,000 of eligible spend coming in the first 2 months that you can spread across both months, and you clear the card every month; you eat out and stay at local hotels a lot and want simple, no-fuss rebates; or you spend heavily on fares and can put HK$4,000 a month on the Octopus Platinum Card.
Skip it: you hold, or have held in the past 12 months, a Citi principal credit card; you're a full-time student at a local tertiary institution; you might cancel within a year; you won't pay a HK$1,800 fee in year two and don't plan to sort it out before the fee is charged; you mostly build spend through Octopus, e-wallet top-ups or bill payments; you travel a lot and mainly spend in foreign currency; or you often pay only the minimum.
FAQ
- How much is the referral welcome offer?
- Depends on the card: HK$1,200 cash rebate on Cash Back, Rewards Mastercard or Rewards UnionPay; HK$1,800 on Octopus Platinum; 240,000 points on PremierMiles; HK$1,000 on HKTVmall; 5,000 Clubpoints on The Club; and up to 720,000 points plus HK$1,200 on Prestige. One per person.
- Who can't join?
- Anyone who holds, or has held or cancelled, any Citi principal credit card in the past 12 months counting from the month of application; full-time students at local tertiary institutions; US persons and residents of the places listed in the terms; and anyone already successfully referred in another Citi referral programme.
- What counts as hitting HK$5,000?
- It builds up over the first 2 months after the card is issued, with at least one eligible transaction each month. Octopus top-ups, e-wallet top-ups, FPS, bill payments, tax, insurance and Citi PayAll don't count. The Octopus Platinum Card also needs at least one HK$500 automatic add-value.
- When does the money land?
- The cash rebate goes onto the new card account within 5 calendar months after the month you hit the target, and the card has to stay valid and in good standing until then.
- What's the latest I can apply?
- Submit the application with the referral code by 4 January 2027 and get approved by 4 February 2027; activate the physical card within 1 month of issue.
- Can I get the year-two annual fee waived?
- Citi only promises the first-year waiver; from year two the Cash Back principal-card fee is HK$1,800 and isn't refunded once paid. If you want to keep the card, ask Citi before the fee is charged.
- What if I cancel within a year?
- Citi can take the face value of the welcome offer back off your card account, and any Cash Back everyday rebate not yet credited is lost when the account closes.
Featured in these guides
Double 12 HK Stacking Playbook — Rewards, Forwarding & Cards on Taobao, JD and HKTVmall
Line up your 12.12 strategy across Taobao, JD.com HK and HKTVmall 篤篤賺: spot what stacks with ShopBack and parcel forwarders, avoid instant tracking voids, and run the HK$ maths on card FX fees.
About 9 minGetting a new iPhone in Hong Kong: check the shop, work out the card bonus and avoid trade-in catches, including Duo
Buying in Hong Kong this November 2026? Check Duo, 18 Pro and Air prices and SIM changes, cashback exclusions, four card offers on an HK$10,499 purchase, and why Trade In can shrink your qualifying spend.
9-minute readJengDeal's Hong Kong card welcome offers, November 2026: lower targets, extended deals and annual fees
Four Hong Kong card referral deals checked on 2026-11-17: Mox E6BZQ2, SC Cathay A3872270, Citi HK and the newly extended Amex Explorer window, with actual spending targets, fee waivers, expired WeWa and the debt-consolidation catch.
9-minute read